
Mining is keystone to the Alaskan economy. In recent years, there has been a renewed interest in developing more mining assets with export potential. But climate change, adverse weather conditions, environmental issues and the sheer remoteness of many of the sites complicate developing the State’s mining resources.
As President Trump offered to buy Greenland last month, he brought into visibility the seven nations whose territories include lands that are north of the Arctic Circle: Canada, Russia, the United States, Norway, Finland, Sweden and Denmark, through its former colony, Greenland. The Arctic nations also include Iceland, with, Grimsey, its northern island, above the Arctic Circle, and, more recently, China – a self-proclaimed “near Arctic state.”
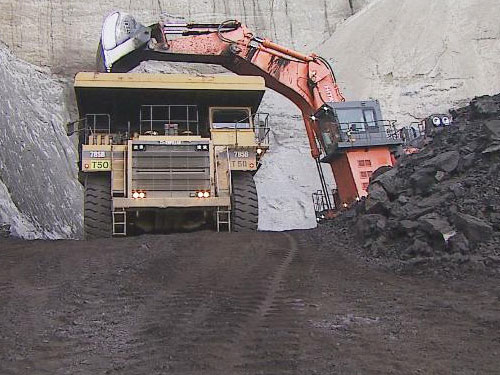
Alaska’s Mineral Wealth
The President could have looked closer to home – to Alaska, which, according to the 2018 Annual Survey of the Fraser Institute, a Canadian public-policy think tank, Alaska ranks in the top five top jurisdictions in the world based on “investment attractiveness” for mining and minerals.
The report noted a distinction between the North American and Russian Arctic regions that ranked highest in mineral potential and the European Arctic Nordic nations with higher scores in government policy. The Fraser authors emphasized the necessity for sound regulations in a political climate that is keenly interested in both environmental impacts and the climate. The report noted corporate interest in “sound regulatory regimes coupled with competitive fiscal policies is key to making a jurisdiction attractive in the eyes of mining investors.” The report also noted a need for improvements: “while jurisdictions cannot change their geology, they can adjust both law and policy.”
The staggering sums needed to start production are far costlier in the Arctic region where efficient design of mines in ice covered, short shipping seasons along with melting permafrost, frostbite, mechanical failures and ice-blocked shipping channels given ice-breakups in the warming waters and, infrastructure that often must be built to accommodate the mining projects.
The Financial Post reported that the rising commodity prices have encouraged companies to accelerate exploration rather than make acquisitions, given the favorable projected growth in consumption – despite the high investment costs in below zero and dark seasonal conditions. For example, companies that spent some $30 million on exploration in Nunavut, Canada twenty years ago, are now investing $325 million in green-field operations where world–class deposits are anticipated.
While Alaskan mining production started with gold in or around 1870s, it remains the second largest gold producing state – after Nevada. Fairbanks, Alaska’s most productive gold district, is the site where more than 10 million ounces of placer gold has been mined, with several new projects in development. Last year, the journal, Resource World, called Alaska mining the “frontier of the future,” where significant discoveries continue in what is viewed as a “relatively unexplored” state with a landmass six times the size of Nevada
Alaska’s long, geologically diverse history with mining includes over 4,400 known gold prospects and more than 2,700 instances of other minerals, including some of the world’s largest deposits. North of 60 Mining News recently reported that Alaska’s geology includes “at least” 29 of the 35 critical minerals and metals that have been identified by the U.S. Geological Survey.
With increasing trade in energy and minerals, shippers who find the northern routes economical, are also aware of the rising risks for shippers where sea-ice is in retreat and what author and Arctic explorer Ed Struzik calls the “formidable challenges” associated with potential for oil spills, groundings, general lack of infrastructure, lack of nearby search and rescue capabilities or, safe harbors.
Global Warming Challenges
Global warming and climate change adds another layer of challenge to producers and shippers alike. With the life of ice roads shortened due to warming, costs rise as equipment must be flown in as melted permafrost makes it harder to operate even broad-tracked vehicles. With few power grids to remote mines, companies must provide their own generated power, build roads to connect to ports, and, in some instances, build a port specific to the mineral being exported.
As warming from the Central Arctic Ocean regions is forcing large chunks of permanent ice into shipping channels causing shippers to rethink how they navigate the highly unchartered waters. With large plugs of ice blocking vessels, it could become worse as calved icebergs drift into shipping lanes, able to tear holes into the sides of the bulk or bulk break vessels.
Such threats are compounded by a dearth of infrastructure along the Alaskan coast. The new roads or rail into the Alaskan interior, compounded by a lack of a deep–water port, such constraints magnify challenging logistics problems, certainly in promising areas for new explorations without spill response, search and rescue and fully equipped safe harbors.
Along with the challenges caused by ice and cold, a rethinking of cost-benefit priorities in terms of environmental impacts is redefining the terrain regarding a series of existing and projects in planning. Communities in the footprint of operations, environmental organizations and some Alaskan Native groups are asking the state, corporate, community and non-governmental entities to consider the trade-offs between the mining bedrock of the Alaskan economy and the environmental impacts of the industry, particularly to the subsistence economies depended upon by many rural Alaskans who hunt, fish, gather and whale for their food security.
The Balance
Decisions are, indeed, complex on this subject. Mining is a key element in the Alaskan economy. In many instances mining provides the only cash income for Alaskans. Many of the State’s major municipalities such as Anchorage, Fairbanks and Nome owe their founding to mining.
Beyond jobs, mining supports both local and the state economy. In 2018, Alaska’s six largest operating mines provided some 9,200 direct and indirect jobs, $715 million in payrolls for some 60 communities, many in rural Alaska where paying jobs are scarce.

Alaska Resource Development Council estimates that the mining industry spent $135 million on exploration in 2018 with an export value of $1.8 billion primarily to China, Japan and India. The industry also accounted for $34 million to local governments, $149 million to state government revenues and $358 million in payments to Alaska Native Corporations.
The flipside, and arguably even raises issues that shippers might engage, is the growing concern being expressed by community leaders and environmental advocates that mining causes substantial harm to marine and terrestrial ecosystems as well as creating food security problems for rural Alaskans. The boxes that accompany this article, reflect on the ecosystem issues in three distinct situations: the lead and zinc Red Dog Mine in northern Alaska, the controversial Pebble Mine, projected to be one of the largest copper, gold and molybdenum mines on the planet, to be located in the headwaters of one of the world’s most productive sockeye salmon fisheries and a graphite-mine-in-planning some forty miles north of Nome, projected as one that could potentially make the U.S. a dominant force in high grade graphite production, and in national security terms, one that would help the U.S. replace China as its sole source for all important graphite to the digital world.
The risks-benefits equation, including a balance of a viable environment in terms of food security and the construction of a “21st century” cash economy is a vital debate, and, indeed, a debate worth having. How it unfolds has everything to do with the future of Alaska, Alaskans, shippers and global commerce – and a conversation being engaged about such tradeoffs worldwide.


