Ocean carriers must recover most of their additional fuel costs or the industry will take a turn from bad to worse.
Cost recovery has already begun for IMO 2020.
RTM Lines, an Ocean Transportation Intermediary (OTI) specializing in breakbulk cargo, has already started levying a bunker surcharge “based on web-based bunker platform reports which will be provided along with the freight invoice,” according to Richard Tiebel, the company’s head of operations. The OTI reserves “the right to adjust [the charges] at time of quotation, time of loading, and at time of discharge,” he added.
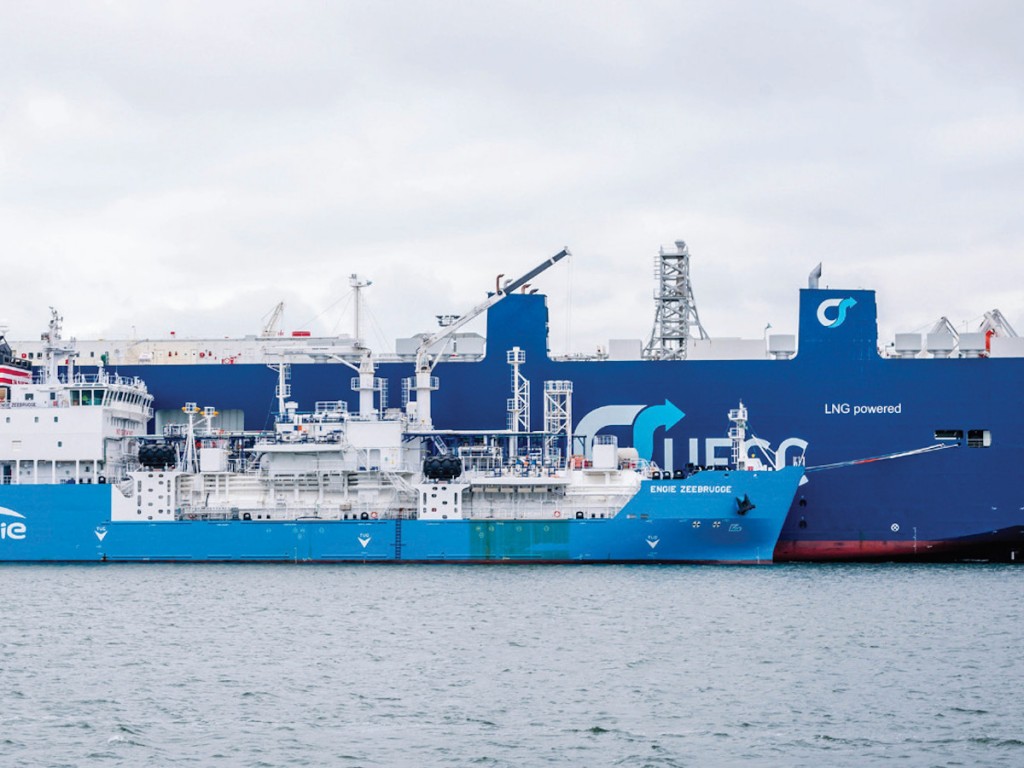
The new IMO regulation, which will enter into force on January 1, 2020, aims to reduce the sulfur oxide (SOx) emissions of the world’s 50,000 merchant ships by 80%. While a positive step for the environment, the IMO implementation will add significant additional costs for carriers, and, by extension, for shippers. Carriers have the option of complying with the regulation in several ways, including burning alternative fuels and implementing technologies that reduce the sulfur content of heavy fuel oil emissions. (See sidebar on page 7)
Breakbulk Sitting on the Sidelines
Breakbulk carriers have lagged behind container lines in implementing IMO-related increases. Maersk and Hamburg Süd both revised their bunker adjustment factors effective January 2019, a full year ahead of the sulfur cap implementation. COSCO Shipping Lines introduced a new monthly-reviewed surcharge effective May 1st. Zim and Crowley were among the other steamship lines that announced rate increases in advance of the IMO requirements.
Whether it is for breakbulk cargo, containers, or other cargo types, the general consensus is that IMO 2020 will increase shipping costs worldwide. Many ships will be burning more expensive fuel, while others will be retrofitted with new technologies such as scrubbers. The maritime consultancy Alphaliner found that carriers in the transpacific trades are taking vessels out of service for extended periods for these retrofits. According to Alphaliner, as many as 90 containerships will be out of the water at any given time during the fourth quarter of this year, resulting in reduced capacity and potentially inflated rates.
It has become clear that carriers need to pass along at least a significant proportion of these increased costs to their customers. “Fuel costs already represent more than 50% of total operating expenses,” said Nikos Petrakakos, vice president of Seabury Maritime, an investment and advisory firm. “IMO 2020 poses an increase too significant for carriers to absorb and stay operational.” A Seabury Maritime analysis showed that shipping a container from China to the United States East Coast will cost $600 more after IMO 2020 takes effect.
The analysts at Drewry believe that carriers will be fairly successful in collecting the surcharges thanks to the wider market acceptance of burden sharing and the fact that carriers started discussing the issue with shippers early on. “It is essential that carriers increase their fuel recovery ratio, or else there will be serious consequences,” said Simon Heaney, Drewry’s senior manager for container research.
A Drewry analysis concurred with Seabury that the ability of carriers to pass on cost increases could be make-or-break for the industry. Under a scenario that assumed carriers would manage to pass on 75% of the cost difference, Drewry’s calculations showed securing the higher rate would lead to a profitable industry in 2020. But under an assumed 50% recovery rate, losses to carriers would result.
IMO 2020 – An Opportunity Docks
As is often the case, business problems yield opportunities in some quarters. One, not surprisingly, is that gasoil exports from the United Arab Emirates are running at recent highs. The biggest rise has been in gasoil bound for Singapore, the world’s largest bunkering port. Gasoil exports bound for Southeast Asia jumped from 10,000 barrels per day in September to 70,000 in October. A year ago, those levels were close to zero.
Another opportunity, this one a bit more surprising, is that the United States is importing record volumes of heavy fuel oil. As prices of high-sulfur fuels sink globally—at $41.56 per barrel on November 6, they reached a three-year low—it has become economical for U.S. concerns to import heavy fuel oil from Russia and former Soviet Union countries, and those reached a multi-year high of 1.35 million tons in October. U.S. ports also received fuel oil from Jordan at the end of October, with another tanker set to arrive around the end of November.
Why the interest in fuel oil that will soon become obsolete? U.S. refiners have greater capability than others around the world to break down cheaper, heavy fuels into higher-margin, compliant products. Their vacuum distillation capacity can break down heavy fuel oil and their coking capacity can upgrade cracked fuel oil. Industry experts say that the increased imports are a sign that U.S. refiners are taking delivery of the heavy fuel oil, as its price declines ahead of the IMO 2020 implementation, in order to upgrade it.
As always, there are also potential snafus associated with the introduction of a new regulatory scheme. LuminUltra, a microbial monitoring specialist, has expressed concerns that reducing sulfur content can result in increased microbial influenced corrosion on vessels. In other words, as Patrick Taylor, LuminUltra’s director of global business development, put it, “Less sulfur means more bugs.”
IMO 2020 Enforcement an Issue
Enforcement of the new rule is also a potential weak spot with reports indicating that some countries might not fully implement IMO 2020. The “enforcement regime is something that is still evolving,” said Sam Ruda, port director at the Port Authority of New York and New Jersey.
The World Shipping Council (WSC) says there must be a level playing field if the regulation is going to work. “We urge any country considering deviation to abandon those ideas,” said John Butler, the WSC CEO.


